Understanding Interest-Only Loans: Are They Right for You?
Choosing the right home loan is one of the most important financial decisions you’ll make. While most borrowers are familiar with principal and interest loans, many are less familiar with interest-only home loans and how they work.
Interest-only loans can offer greater flexibility and lower repayments during the initial years of a loan. However, they aren’t suitable for everyone and should be considered carefully.
In this guide, we’ll explain what an interest-only loan is, how it works, its advantages and disadvantages, and the situations in which it may be an appropriate lending strategy.
What Is an Interest-Only Loan?
An interest-only loan allows borrowers to pay only the interest charged on the loan for a specified period.
Unlike a traditional principal and interest loan, your repayments during the interest-only period do not reduce the original loan amount.
For example:
| Loan Details | Principal & Interest | Interest-Only |
|---|---|---|
| Loan amount | $600,000 | $600,000 |
| Interest rate | 6% | 6% |
| Repayments | Principal + interest | Interest only |
| Loan balance after 5 years | Reduced | Still $600,000 |
Most lenders in Australia offer interest-only periods of between one and five years.
Once the interest-only period ends, the loan automatically converts to principal and interest repayments.
How Does an Interest-Only Loan Work?
Let’s assume you borrow $700,000 with a 30-year loan term and choose a five-year interest-only period.
During the first five years:
- You’ll only pay interest.
- Your monthly repayments will be lower.
- Your loan balance won’t decrease.
After five years:
- The loan converts to principal and interest.
- You’ll have only 25 years remaining to repay the loan.
- Your monthly repayments will increase significantly.
Understanding this transition is essential when considering an interest-only strategy.
Advantages of Interest-Only Loans
Lower Monthly Repayments
Because you’re not repaying the principal during the interest-only period, your monthly repayments are lower.
This can improve cash flow and provide greater financial flexibility.
Increased Investment Opportunities
Many property investors choose interest-only loans because lower repayments allow them to:
- Purchase additional properties.
- Invest in renovations.
- Build investment portfolios.
Greater Cash Flow Flexibility
Borrowers may use the additional cash flow to:
- Build emergency savings.
- Invest in shares.
- Reduce other high-interest debt.
- Fund business activities.
Potential Tax Benefits for Investors
For investment properties, interest payments may be tax-deductible.
Many investors use interest-only loans as part of a broader tax and investment strategy.
Professional tax advice should always be obtained before making investment decisions.
Disadvantages of Interest-Only Loans
Higher Long-Term Costs
Although repayments are lower initially, you’ll usually pay more interest over the life of the loan.
No Equity Growth Through Repayments
Because you’re not reducing the principal balance, you’re not building equity through repayments.
The only increase in equity comes from property appreciation.
Repayment Shock
One of the biggest risks is the sudden increase in repayments after the interest-only period ends.
Many borrowers underestimate how much their repayments will increase.
Stricter Lending Requirements
Australian lenders typically apply stricter lending criteria to interest-only loans.
Borrowers may need:
- Higher incomes.
- Larger deposits.
- Stronger financial positions.
Who Should Consider an Interest-Only Loan?
Property Investors
Investors often use interest-only loans to maximize cash flow and minimize repayments during the early stages of an investment strategy.
Borrowers Expecting Short-Term Financial Changes
An interest-only loan may be suitable if you expect:
- A temporary reduction in income.
- Maternity leave.
- Career changes.
- Temporary financial commitments.
Borrowers Planning to Sell
If you plan to sell a property within a few years, lower short-term repayments may be beneficial.
Who Should Avoid Interest-Only Loans?
An interest-only loan may not be suitable if:
- You’re buying your first home.
- You’re focused on paying off your mortgage quickly.
- You’re uncomfortable with future repayment increases.
- You have limited financial reserves.
Interest-Only vs. Principal and Interest Loans
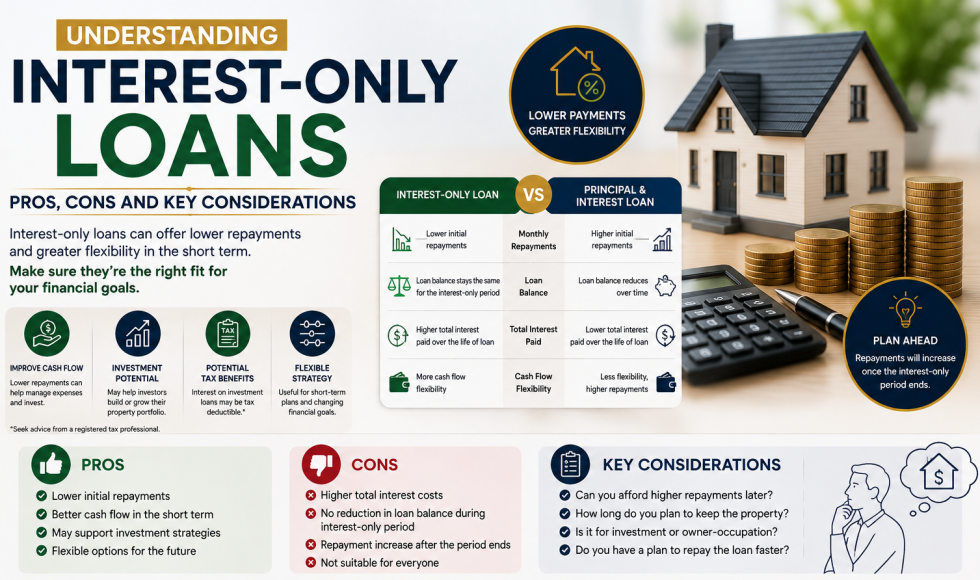
| Feature | Interest-Only | Principal & Interest |
|---|---|---|
| Initial repayments | Lower | Higher |
| Equity growth | Slower | Faster |
| Total interest paid | Higher | Lower |
| Investment flexibility | Greater | Moderate |
| Long-term affordability | Lower | Higher |
Questions to Ask Before Choosing an Interest-Only Loan
Before deciding, ask yourself:
- Can I afford higher repayments in the future?
- How long do I plan to keep the property?
- Am I buying a home or an investment property?
- What are my long-term financial goals?
Final Thoughts
Interest-only loans can be a valuable financial tool when used appropriately. However, they should form part of a broader financial strategy rather than being chosen solely because of their lower initial repayments.
At Suncrest Finance, we help borrowers understand their options and choose lending solutions that align with their financial goals.
Whether you’re purchasing your first investment property or exploring refinancing opportunities, we’re here to help you make informed borrowing decisions.
Need help deciding whether an interest-only loan is right for you? Contact Suncrest Finance for professional, personalized mortgage advice.
3 Comments
Riva Collins
December 25, 2018 - 3:33 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghor global and brands, companies are reaching out.
Obila Doe
December 25, 2018 - 3:42 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghorglobal and brands, companies are reaching out.
Arnold Rio
December 25, 2018 - 3:44 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghorglobal and brands, companies are reaching out.