Investment Property Loan Strategies: A Guide to Building Long-Term Wealth
Property investment continues to be one of the most popular wealth-building strategies in Australia. Whether you’re purchasing your first investment property or expanding an existing portfolio, choosing the right loan structure can significantly influence your long-term financial success.
Many investors focus primarily on finding the right property while overlooking the importance of selecting an appropriate financing strategy. However, the structure of your loan can affect your cash flow, tax position, borrowing capacity, investment returns, and future opportunities.
An effective investment property loan strategy goes beyond simply obtaining the lowest interest rate. It involves creating a financing solution that supports your short-term objectives while helping you achieve your long-term financial goals.
In this guide, we’ll explore the most effective investment property loan strategies, explain how they work, and discuss the factors every Australian property investor should consider.
Why Your Investment Loan Strategy Matters
An investment property is different from an owner-occupied home.
When purchasing a family home, most borrowers focus on affordability and paying off the mortgage as quickly as possible.
Investment properties, on the other hand, are designed to generate income and build wealth over time.
Your loan strategy can influence:
- Monthly cash flow
- Tax benefits
- Borrowing power
- Equity growth
- Portfolio expansion
- Risk management
A well-structured investment loan can help you maximize opportunities while minimizing unnecessary costs.
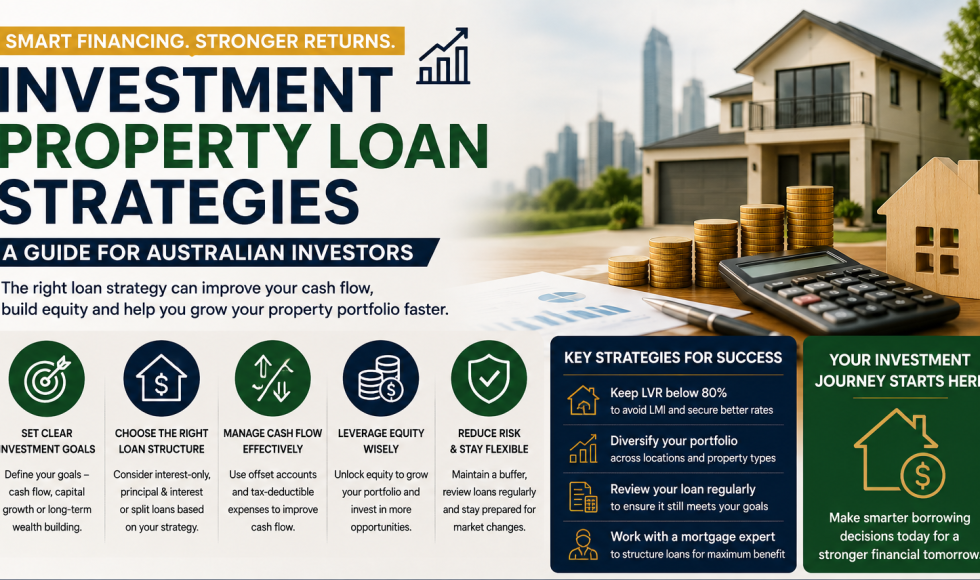
Understand Your Investment Goals
Before comparing lenders and loan products, define your investment objectives.
Ask yourself:
- Are you seeking rental income?
- Are you investing for long-term capital growth?
- Do you plan to purchase multiple properties?
- Are you building a retirement portfolio?
- Are you interested in positive or negative gearing?
Your answers will determine which loan structure is most suitable.
Choose Between Principal and Interest or Interest-Only Loans
One of the first decisions investors must make is whether to choose a principal and interest loan or an interest-only loan.
Principal and Interest Loans
With a principal and interest loan, your repayments reduce both the loan balance and the interest charged.
Advantages:
- Faster equity growth
- Lower interest costs over time
- Reduced long-term debt
Disadvantages:
- Higher monthly repayments
- Reduced short-term cash flow
Interest-Only Loans
An interest-only loan allows you to pay only the interest for a specified period.
Advantages:
- Lower repayments
- Improved cash flow
- Greater flexibility
Disadvantages:
- Higher overall interest costs
- No reduction in the principal balance during the interest-only period
Many Australian property investors choose interest-only loans because they provide greater flexibility during the early years of ownership.
Use an Offset Account to Improve Cash Flow
An offset account is one of the most powerful tools available to property investors.
An offset account is a transaction account linked to your home loan.
The balance in the offset account reduces the amount of the loan on which interest is calculated.
Example:
Loan balance:
$700,000
Offset account balance:
$50,000
Interest is calculated on:
$650,000 instead of $700,000.
Benefits of an Offset Account
Reduce Interest
The more money you keep in your offset account, the less interest you’ll pay.
Maintain Access to Your Funds
Unlike making additional loan repayments, money held in an offset account remains accessible.
Improve Investment Flexibility
Investors can use offset funds for:
- Future property purchases
- Renovations
- Emergency expenses
- Investment opportunities
Understand Loan-to-Value Ratio (LVR)
Your Loan-to-Value Ratio (LVR) compares your loan amount with the property’s value.
The formula is:
LVR = Loan Amount ÷ Property Value × 100
Why LVR Is Important
Lenders use your LVR to assess risk.
Lower LVR (Below 80%)
- Better interest rates
- Lower borrowing costs
- No Lenders Mortgage Insurance (LMI)
Higher LVR (Above 80%)
- Increased lending risk
- Possible LMI costs
- Fewer loan options
Many investors aim to keep their LVR below 80% to avoid paying LMI.
Use Equity to Expand Your Portfolio
One of the greatest advantages of property investment is the ability to use equity to acquire additional properties.
Equity is the difference between your property’s market value and your outstanding loan balance.
Example:
Property value:
$900,000
Outstanding mortgage:
$600,000
Available equity:
$300,000
Rather than saving another deposit, investors may use available equity to:
- Purchase additional properties
- Fund renovations
- Diversify investments
However, equity should be used carefully to avoid overextending your finances.
Consider Fixed, Variable, or Split Loans
Interest rate selection can have a significant impact on your investment strategy.
Fixed Interest Rates
A fixed-rate loan locks your interest rate for a specified period.
Advantages:
- Predictable repayments
- Protection against interest rate increases
Disadvantages:
- Less flexibility
- Break costs may apply
Variable Interest Rates
Variable rates fluctuate according to market conditions.
Advantages:
- Greater flexibility
- Offset account access
- Additional repayment options
Disadvantages:
- Repayments may increase
Split Loans
A split loan combines fixed and variable interest rates.
Advantages:
- Greater flexibility
- Protection against rising interest rates
- Access to offset accounts
Many investors use split loans to balance stability and flexibility.
Understand Negative and Positive Gearing
Negative Gearing
A property is negatively geared when rental income doesn’t cover investment expenses.
Advantages:
- Potential tax deductions
- Greater focus on capital growth
Risks:
- Ongoing cash flow requirements
- Dependence on property appreciation
Positive Gearing
A property is positively geared when rental income exceeds expenses.
Advantages:
- Positive cash flow
- Additional income
Risks:
- Higher taxes on rental profits
- Potentially lower growth opportunities
Understanding your cash flow position is essential when choosing an investment strategy.
Maintain a Financial Buffer
Property investing involves risk.
Unexpected events may include:
- Interest rate increases
- Vacancies
- Repairs
- Maintenance expenses
- Economic changes
Successful investors maintain an emergency fund to cover unexpected costs.
A financial buffer can help protect your investment during challenging periods.
Avoid Cross-Collateralisation
Cross-collateralisation occurs when multiple properties are used as security under one loan arrangement.
Although this may seem convenient, it can reduce flexibility.
Potential disadvantages include:
- Limited refinancing options
- Reduced control over individual properties
- More complex selling processes
Many mortgage brokers recommend separate loan structures for each investment property.
Review Your Loan Regularly
Your investment loan shouldn’t remain unchanged for decades.
Interest rates, property values, lending policies, and personal circumstances change over time.
Review your loan regularly to determine whether:
- A better interest rate is available
- Refinancing could reduce costs
- Equity can be used more effectively
- Your investment goals have changed
Many investors conduct annual loan reviews.
Common Investment Loan Mistakes
Avoid these common mistakes:
Focusing Only on Interest Rates
The cheapest loan isn’t always the best loan.
Borrowing Beyond Your Means
Higher borrowing doesn’t always mean better investment opportunities.
Ignoring Cash Flow
Rental income doesn’t guarantee profitability.
Overlooking Additional Costs
Remember to consider:
- Stamp duty
- Legal fees
- Property management fees
- Insurance
- Maintenance costs
Failing to Seek Professional Advice
Property investment involves lending, taxation, legal requirements, and financial planning.
Professional advice can help you avoid costly mistakes.
How a Mortgage Broker Can Help
A mortgage broker can help investors:
- Compare multiple lenders
- Structure loans appropriately
- Access competitive rates
- Review borrowing capacity
- Identify suitable loan features
At Suncrest Finance, we work with clients to develop lending strategies that align with their property investment goals.
Whether you’re purchasing your first investment property or expanding your portfolio, our goal is to help you make informed financial decisions.
Final Thoughts
A successful investment property strategy requires more than simply finding the right property.
Choosing the right loan structure can improve cash flow, increase flexibility, reduce borrowing costs, and create opportunities for future growth.
There is no one-size-fits-all solution.
Every investor has different goals, risk tolerances, and financial circumstances.
Understanding your options and seeking professional advice can help you build a stronger property portfolio and achieve long-term financial success.
If you’re considering an investment property, Suncrest Finance can help you explore your lending options and develop a financing strategy tailored to your needs.
Frequently Asked Questions (FAQ)
What is the best loan for an investment property?
The best loan depends on your investment goals, cash flow requirements, and long-term strategy. Many investors choose loans that provide flexibility through offset accounts and additional repayment options.
Should I choose an interest-only investment loan?
Interest-only loans may improve cash flow, but they can increase long-term borrowing costs. Professional advice is recommended before making a decision.
Can I use equity to buy another investment property?
Yes. Many investors use available equity from existing properties to fund future purchases.
Do investment properties qualify for tax benefits?
Certain investment expenses may be tax-deductible. Always seek advice from a qualified tax professional.