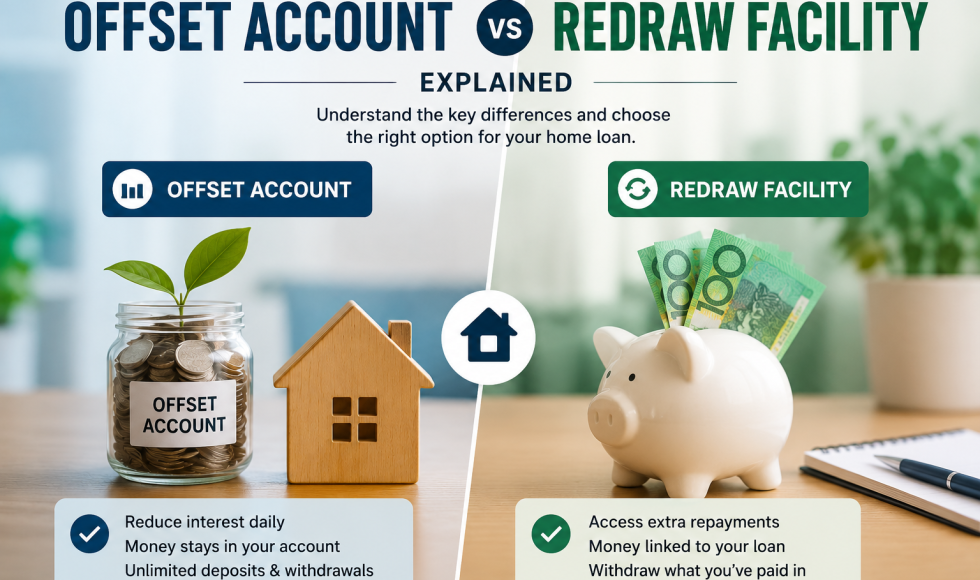
Understanding Offset Accounts and Redraw Facilities.
When comparing home loans, many borrowers focus primarily on the interest rate. While interest rates are important, loan features can also have a significant impact on how much interest you pay over the life of your loan.
Two of the most common home loan features offered by Australian lenders are offset accounts and redraw facilities.
At first glance, both can help reduce interest costs. However, they work differently and may suit different financial situations.
In this guide, we’ll explain how offset accounts and redraw facilities work, their advantages and disadvantages, and how to determine which option may be right for you.
What Is an Offset Account?
An offset account is a transaction or savings account linked to your home loan.
The balance held in the offset account is used to reduce the amount of your loan on which interest is calculated.
Importantly, the money remains accessible whenever you need it.
Example
Let’s assume:
- Home loan balance: $700,000
- Offset account balance: $50,000
Instead of calculating interest on $700,000, the lender calculates interest on:
$700,000 – $50,000 = $650,000
As a result, you pay less interest while maintaining full access to your savings.
How Does an Offset Account Save Money?
Because interest is calculated on a lower effective loan balance, more of your repayments go toward reducing the principal.
Over time, this can:
- Reduce total interest paid
- Help pay off the loan sooner
- Improve cash flow
- Build equity faster
Even modest savings held consistently in an offset account can generate substantial long-term savings.
Benefits of an Offset Account
Full Access to Your Money
Unlike some loan structures, your funds remain available whenever needed.
You can generally:
- Transfer money
- Pay bills
- Withdraw cash
- Use debit card facilities
This flexibility makes offset accounts attractive for many homeowners.
Interest Savings Without Locking Funds Away
You receive the benefit of reducing loan interest while retaining liquidity.
This can be useful for:
- Emergency savings
- Renovation plans
- Future investments
- Family expenses
Potential Tax Advantages for Investors
For property investors, offset accounts can sometimes provide greater flexibility than making direct extra repayments.
Because tax circumstances vary, borrowers should seek advice from a qualified tax professional regarding their individual situation.
Simplified Money Management
Many borrowers use their offset account as their primary transaction account.
By depositing salary and managing day-to-day expenses through the offset account, they can maximise interest savings automatically.
What Is a Redraw Facility?
A redraw facility allows borrowers to access extra repayments they have previously made on their home loan.
If you’ve paid more than the required minimum repayment, those additional funds may be available to withdraw later.
Example
Required monthly repayment:
$4,200
You choose to pay:
$5,000
Extra repayment:
$800 per month
After 12 months:
$9,600 in additional repayments may be available for redraw (subject to lender policies and conditions).
How Does Redraw Save Money?
Every additional repayment immediately reduces your loan balance.
As the balance decreases:
- Interest is charged on a smaller amount
- Interest costs reduce
- More of your repayment goes toward principal reduction
This helps accelerate mortgage repayment and can significantly reduce long-term interest expenses.
Benefits of a Redraw Facility
Reduce Interest Costs
Every extra dollar paid into the loan directly reduces the principal balance.
This can result in meaningful interest savings over time.
Faster Loan Repayment
Consistent additional repayments can help borrowers become debt-free sooner.
Access to Extra Funds If Needed
If circumstances change, borrowers may be able to access previously paid extra funds.
Common reasons include:
- Home improvements
- Unexpected expenses
- Education costs
- Vehicle purchases
Usually No Separate Account Required
Unlike offset accounts, redraw facilities generally operate within the loan itself, keeping things simple.
Limitations of Redraw Facilities
Access May Be Restricted
Unlike an offset account, redraw funds are not always immediately available.
Some lenders may:
- Set minimum redraw amounts
- Limit online access
- Require processing time
- Restrict access under certain conditions
Funds Are Inside the Loan
The money has already been applied to reduce your loan balance.
Although it may be available for redraw, accessing it may involve additional steps.
Policies Differ Between Lenders
Redraw features vary significantly across lenders.
Understanding the lender’s terms and conditions is important before relying on redraw access.
Offset Account vs Redraw Facility: Key Differences
| Feature | Offset Account | Redraw Facility |
|---|---|---|
| Reduces Interest | Yes | Yes |
| Access to Funds | Immediate | May be restricted |
| Separate Bank Account | Yes | No |
| Everyday Transactions | Yes | No |
| Emergency Fund Suitable | Excellent | Moderate |
| Loan Repayment Acceleration | Yes | Yes |
| Flexibility | High | Moderate |
Which Option Saves More Interest?
This is one of the most common questions borrowers ask.
In many situations, if the same amount of money is held consistently, the interest savings may be very similar.
For example:
- $20,000 held in an offset account
- $20,000 paid as extra repayments into a redraw facility
Both may reduce interest calculations by a comparable amount.
The biggest difference often comes down to flexibility and access to funds.
Who Should Consider an Offset Account?
An offset account may suit borrowers who:
- Maintain regular savings balances
- Want quick access to their money
- Prefer greater financial flexibility
- Have variable income
- Like having an emergency fund available
Many owner-occupiers and investors value offset accounts because they combine flexibility with interest savings.
Who Should Consider a Redraw Facility?
A redraw facility may suit borrowers who:
- Are focused on paying down debt quickly
- Don’t need frequent access to funds
- Prefer a simpler loan structure
- Consistently make additional repayments
For disciplined borrowers, redraw can be an effective tool for accelerating mortgage repayment.
Can You Have Both?
Some lenders offer home loans that include both:
- An offset account
- A redraw facility
This can provide the benefits of both features and greater flexibility.
However, loan features, fees, and eligibility requirements vary between lenders.
Common Mistakes Borrowers Make
Choosing Based Only on Interest Rate
A slightly lower interest rate may not always provide the best overall value if important features are missing.
Not Understanding Access Restrictions
Borrowers sometimes assume redraw funds can always be accessed instantly.
It’s important to understand your lender’s policies.
Leaving Savings in Low-Interest Accounts
Holding large savings balances outside an offset account may mean missing opportunities to reduce home loan interest.
Failing to Review Loan Features
Your financial needs may change over time.
Regularly reviewing your loan can help ensure it continues to support your goals.
Real-Life Example
Consider two borrowers:
Sarah
- Mortgage: $650,000
- Savings: $40,000
- Uses an offset account
Sarah keeps her emergency fund available while reducing interest charged on her loan.
Michael
- Mortgage: $650,000
- Makes extra repayments of $40,000
- Uses redraw
Michael focuses on paying down debt faster while retaining access to additional funds if required.
Both strategies can be effective depending on individual circumstances and priorities.
The Bottom Line
Both offset accounts and redraw facilities can help reduce interest costs and improve long-term mortgage outcomes.
An offset account generally offers greater flexibility and easier access to funds, while a redraw facility can be an effective way to accelerate loan repayment through additional contributions.
The right option depends on your financial goals, cash flow needs, and personal preferences.
When comparing home loans, it’s important to look beyond the interest rate and consider the features that may support your financial objectives over the long term.
Need Help Choosing the Right Home Loan Features?
At Suncrest Finance, we help borrowers compare home loan products and understand the features that may be most beneficial for their circumstances.
Whether you’re purchasing your first home, refinancing an existing loan, or building an investment portfolio, we’re here to help you make informed lending decisions.
Contact Suncrest Finance today for a complimentary home loan consultation.
3 Comments
Riva Collins
December 25, 2018 - 3:33 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghor global and brands, companies are reaching out.
Obila Doe
December 25, 2018 - 3:42 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghorglobal and brands, companies are reaching out.
Arnold Rio
December 25, 2018 - 3:44 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghorglobal and brands, companies are reaching out.