First Home Buyer Guide for Australians: Everything You Need to Know Before Buying Your First Home.
Introduction
Buying your first home is one of the biggest financial decisions you’ll ever make. It’s exciting, rewarding, and for many Australians, a major milestone toward building long-term financial security.
However, the process can also feel overwhelming.
Questions such as:
- How much can I borrow?
- How much deposit do I need?
- What government assistance is available?
- What are the hidden costs?
- Should I get pre-approval first?
are common among first home buyers.
The good news is that with the right planning and guidance, the process becomes much easier to understand and navigate.
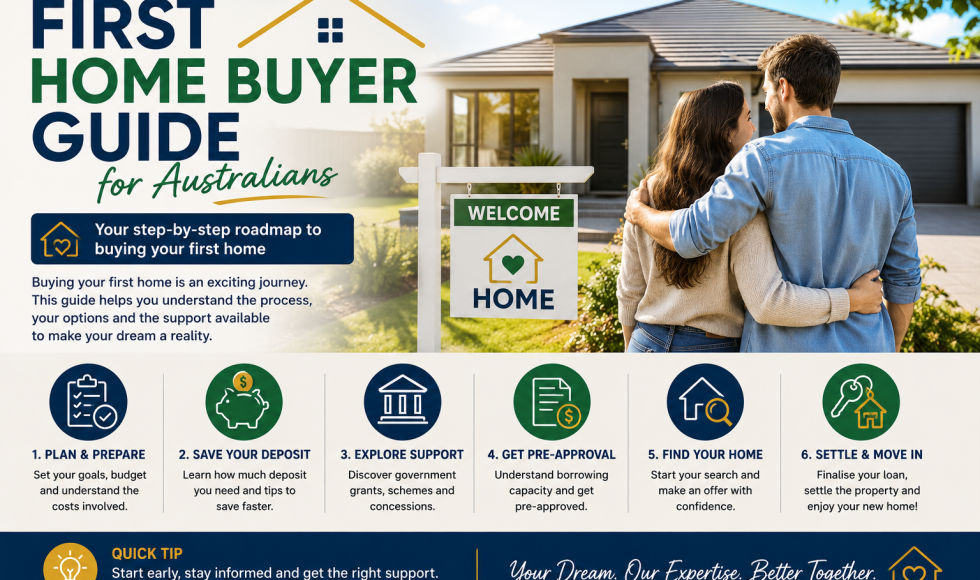
This guide walks you through everything you need to know before purchasing your first home in Australia.
Step 1: Understand Your Financial Position
Before looking at properties, it’s important to understand your current financial situation.
Start by reviewing:
Your Income
Lenders will assess:
- Salary and wages
- Overtime and allowances
- Bonuses
- Rental income (if applicable)
- Other regular income sources
Your Expenses
Lenders also assess your spending habits.
This includes:
- Living expenses
- Utilities
- Insurance
- Childcare
- Transport costs
- Existing loan repayments
Having a clear understanding of your monthly expenses will help determine what repayments you can comfortably afford.
Your Existing Debts
Current debts may impact borrowing capacity.
Examples include:
- Credit cards
- Personal loans
- Car loans
- Buy Now Pay Later accounts
Reducing debt before applying can strengthen your loan application.
Step 2: Determine How Much Deposit You Have
Your deposit is the amount you contribute toward the purchase price.
Generally, larger deposits can:
- Improve borrowing options
- Reduce lender risk
- Lower repayments
- Help avoid Lenders Mortgage Insurance (LMI)
Many first home buyers aim for:
- 5% deposit
- 10% deposit
- 20% deposit
The amount required depends on lender policies and your circumstances.
Example Deposit Requirements
| Property Price | 5% Deposit | 10% Deposit | 20% Deposit |
|---|---|---|---|
| $700,000 | $35,000 | $70,000 | $140,000 |
| $900,000 | $45,000 | $90,000 | $180,000 |
| $1,200,000 | $60,000 | $120,000 | $240,000 |
Remember to budget for additional purchasing costs as well.
Step 3: Understand Additional Buying Costs
Many first home buyers focus only on the deposit and forget about other expenses.
Common costs include:
Stamp Duty
Depending on your state or territory, stamp duty can be a significant expense.
Some first home buyers may qualify for concessions or exemptions.
Conveyancing Fees
A conveyancer or solicitor manages the legal transfer of ownership.
Building and Pest Inspections
These inspections can help identify potential issues before committing to a purchase.
Loan Establishment Fees
Some lenders charge setup or application fees.
Moving Costs
Removalists, utility connections, and other relocation expenses should also be considered.
Step 4: Check Your Credit Position
Your credit profile plays an important role in the loan approval process.
Lenders review:
- Credit enquiries
- Existing liabilities
- Repayment history
- Defaults or adverse credit events
Tips to Improve Your Credit Position
Pay Bills on Time
Consistent repayment history demonstrates responsible financial behaviour.
Reduce Credit Card Limits
Higher limits may affect borrowing capacity even if balances are low.
Avoid Multiple Loan Applications
Too many credit enquiries in a short period can raise concerns with lenders.
Check Your Credit Report
Reviewing your report allows you to identify and address any inaccuracies.
Step 5: Understand Borrowing Capacity
Borrowing capacity refers to how much a lender may be willing to lend.
This depends on factors including:
- Income
- Expenses
- Existing debts
- Number of dependants
- Credit profile
- Interest rate buffers
Every lender assesses borrowing capacity differently.
A professional assessment can help provide a clearer understanding of your borrowing potential.
Step 6: Explore Government Assistance Programs
Several government initiatives may help eligible first home buyers enter the property market sooner.
First Home Guarantee
This scheme allows eligible buyers to purchase a home with a smaller deposit without paying Lenders Mortgage Insurance.
Places are limited and eligibility requirements apply.
First Home Super Saver Scheme
Allows eligible Australians to save for a deposit through voluntary superannuation contributions.
Potential benefits include:
- Tax-effective savings
- Faster deposit accumulation
State-Based Assistance
Depending on where you purchase, assistance may include:
- Stamp duty concessions
- Grants
- Regional incentives
Eligibility requirements vary by location.
Step 7: Obtain Home Loan Pre-Approval
Pre-approval provides an indication of how much you may be able to borrow before purchasing a property.
Benefits of Pre-Approval
Greater Confidence
You’ll know your approximate budget before house hunting.
Faster Decision Making
You can make offers with greater confidence.
Improved Negotiation Position
Sellers and agents often view pre-approved buyers more favourably.
Reduced Stress
You can focus on properties within your borrowing range.
Step 8: Choose the Right Home Loan
Not all home loans are the same.
When comparing options, consider:
Interest Rate
Fixed, variable, or split loan options.
Offset Accounts
Can help reduce interest while maintaining access to savings.
Redraw Facilities
Allow access to extra repayments made on the loan.
Loan Flexibility
Consider future needs such as refinancing or making additional repayments.
Fees and Charges
Look beyond the advertised interest rate.
Consider:
- Annual fees
- Application fees
- Ongoing fees
Step 9: Start House Hunting
Once you understand your budget and have pre-approval, you can begin searching for suitable properties.
Consider:
Location
- Commute times
- Schools
- Public transport
- Future development
Property Type
- House
- Townhouse
- Apartment
Lifestyle Needs
Think about both current and future requirements.
Step 10: Make an Offer
Once you’ve found the right property, you’ll need to make an offer or participate in an auction process.
Before committing:
- Review contracts carefully
- Seek legal advice
- Confirm finance arrangements
- Complete inspections where appropriate
Step 11: Formal Loan Approval
After signing a contract, your lender will complete:
Property Valuation
The lender confirms the property’s value.
Final Assessment
All documentation is reviewed before approval.
Loan Documentation
You’ll receive documents outlining the loan terms and conditions.
Step 12: Settlement
Settlement is the final stage of the home buying process.
At settlement:
- Loan funds are released
- Ownership transfers
- Mortgage registration occurs
Once settlement is complete, you officially become a homeowner.
Common First Home Buyer Mistakes
Borrowing the Maximum Amount
Just because a lender will approve a certain amount doesn’t mean it’s comfortable for your budget.
Ignoring Future Expenses
Home ownership includes ongoing costs such as:
- Rates
- Insurance
- Maintenance
- Repairs
Not Shopping Around
Different lenders can offer different rates, policies, and features.
Rushing the Process
Taking time to understand your options can lead to better long-term outcomes.
Focusing Only on Interest Rates
Features such as offset accounts, redraw facilities, and loan flexibility can be equally important.
Frequently Asked Questions
How Much Deposit Do I Need?
Many lenders offer options for borrowers with deposits below 20%, subject to eligibility requirements.
Do I Need Pre-Approval?
While not mandatory, pre-approval can make the buying process smoother and more efficient.
What Is Lenders Mortgage Insurance (LMI)?
LMI is insurance that protects the lender when borrowers have smaller deposits.
Can I Buy a Home with a 5% Deposit?
Some borrowers may be eligible to purchase with a 5% deposit depending on lender policies and government schemes.
Why Use a Mortgage Broker as a First Home Buyer?
A mortgage broker can help:
- Compare multiple lenders
- Explain loan options
- Guide you through the application process
- Assist with documentation
- Help identify suitable government programs
Rather than approaching a single bank, a broker can provide access to a broader range of lending solutions.
The Bottom Line
Buying your first home can seem complex, but breaking the process into manageable steps makes it far more achievable.
Understanding your finances, saving a deposit, obtaining pre-approval, comparing loan options, and seeking professional guidance can significantly improve your confidence and decision-making.
With the right preparation, home ownership may be closer than you think.
Ready to Buy Your First Home?
At Suncrest Finance, we help first home buyers understand their borrowing options, navigate government assistance programs, compare lenders, and move through the home loan process with confidence.
Whether you’re just beginning your savings journey or ready to purchase your first property, we’re here to help.
Contact Suncrest Finance today for a complimentary first home buyer consultation and take the next step toward owning your home.
3 Comments
Riva Collins
December 25, 2018 - 3:33 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghor global and brands, companies are reaching out.
Obila Doe
December 25, 2018 - 3:42 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghorglobal and brands, companies are reaching out.
Arnold Rio
December 25, 2018 - 3:44 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghorglobal and brands, companies are reaching out.