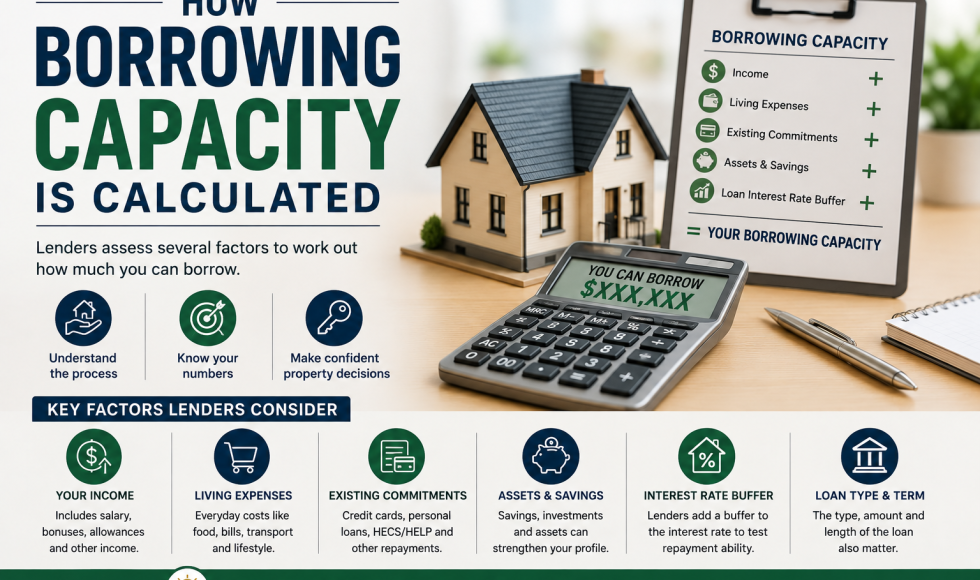
How Borrowing Capacity Is Calculated: Understanding How Much You Can Borrow for a Home Loan.
Introduction
One of the first questions most home buyers ask is:
“How much can I borrow?”
Whether you’re buying your first home, refinancing, upgrading to a larger property, or purchasing an investment property, understanding your borrowing capacity is a crucial first step.
Many borrowers are surprised to learn that borrowing capacity is not based solely on income. Lenders consider a range of factors including your expenses, debts, credit history, employment situation, and financial commitments.
In this guide, we’ll explain how borrowing capacity is calculated, what factors affect it, and how you may be able to improve your borrowing power before applying for a home loan.
What Is Borrowing Capacity?
Borrowing capacity refers to the amount a lender may be willing to lend based on an assessment of your financial situation.
Each lender uses its own assessment criteria and servicing models, which means borrowing limits can vary significantly between lenders.
As a result, two lenders may offer very different borrowing amounts for the same borrower.
Understanding borrowing capacity early can help you:
- Set a realistic property budget
- Avoid disappointment during house hunting
- Improve your chances of loan approval
- Identify areas where you can strengthen your application
Why Borrowing Capacity Matters
Knowing how much you can borrow helps you make informed decisions before committing to a property purchase.
It allows you to:
Shop Within Your Budget
Understanding your borrowing limit helps focus your property search on realistic options.
Avoid Overcommitting Financially
Just because a lender approves a certain amount doesn’t necessarily mean it’s comfortable for your personal circumstances.
Improve Negotiating Confidence
Buyers who understand their financial position are often better prepared when making offers.
Streamline the Home Loan Process
Knowing your borrowing capacity early can make obtaining pre-approval and formal approval more efficient.
Key Factors That Affect Borrowing Capacity
Lenders assess multiple aspects of your financial profile.
1. Your Income
Income is one of the most important factors.
Lenders may consider:
Employment Income
- Full-time salary
- Part-time income
- Casual employment income
- Contract income
Additional Income Sources
Depending on lender policies, income may also include:
- Overtime
- Bonuses
- Commissions
- Rental income
- Investment income
- Government benefits
Not all lenders assess these income sources in the same way.
2. Your Living Expenses
In recent years, lenders have placed greater emphasis on living expenses.
Borrowers are generally required to disclose expenses such as:
- Food and groceries
- Utilities
- Insurance
- Transport
- Education costs
- Childcare
- Entertainment
- Subscriptions
Lenders compare declared expenses against industry benchmarks and their own assessment models.
Higher living expenses may reduce borrowing capacity.
3. Existing Debts
Current financial commitments can significantly impact borrowing power.
Examples include:
Credit Cards
Even if a credit card balance is zero, lenders often assess the full credit limit as a potential liability.
Example:
Credit Card Limit: $20,000
Many lenders assess this as a financial commitment regardless of the current balance.
Personal Loans
Existing personal loan repayments reduce available servicing capacity.
Car Loans
Vehicle finance commitments are included in lender calculations.
Buy Now Pay Later Accounts
Services such as Afterpay, Zip, and similar facilities may also affect assessments.
4. Number of Dependants
Lenders consider household composition when assessing affordability.
Generally, larger households have higher living costs.
Examples:
- Single applicant
- Couple with no children
- Family with multiple dependants
Additional dependants may reduce borrowing capacity because household expenses are typically higher.
5. Employment Stability
Lenders generally prefer borrowers with stable employment histories.
Factors considered may include:
Length of Employment
Longer employment history can strengthen an application.
Employment Type
- Permanent employment
- Casual employment
- Contract employment
- Self-employment
Different employment types may require different documentation.
6. Credit History
Lenders review your credit profile to assess borrowing risk.
They may consider:
- Repayment history
- Credit enquiries
- Existing liabilities
- Defaults
- Court judgments
- Bankruptcy history
A strong credit profile may improve loan options and approval prospects.
7. Loan Term
The length of the loan can affect borrowing capacity.
Common loan terms include:
- 25 years
- 30 years
Longer terms may reduce monthly repayment requirements, which can influence servicing calculations.
Understanding Serviceability
One of the most important concepts in home lending is serviceability.
Serviceability measures whether a borrower can comfortably meet loan repayments based on their financial situation.
Lenders assess:
- Current income
- Current expenses
- Existing debts
- Future loan repayments
The goal is to ensure borrowers can manage repayments both now and in the future.
What Is an Interest Rate Buffer?
Australian lenders typically assess borrowers using an interest rate higher than the actual loan rate.
This is known as a serviceability buffer.
For example:
Actual Interest Rate: 6.00%
Assessment Rate: 9.00%
This helps ensure borrowers can continue making repayments if interest rates rise in the future.
Because of this buffer, borrowers may not qualify for the full amount they expect based on current rates alone.
Why Different Lenders Offer Different Borrowing Amounts
Many borrowers assume all lenders calculate borrowing capacity in the same way.
This is not the case.
Lenders differ in:
- Income treatment
- Expense assessment
- Rental income calculations
- Credit card treatment
- Self-employed policies
- Serviceability models
As a result, borrowing capacity can vary significantly across lenders.
This is one reason many borrowers choose to work with a mortgage broker who can compare multiple lender options.
Example Borrowing Capacity Scenario
Let’s assume:
Combined Household Income: $180,000
Existing Car Loan: $500 per month
Credit Card Limit: $15,000
Two Dependants
Moderate Living Expenses
Depending on lender policies, borrowing capacity may vary considerably.
The purpose of this example is not to provide exact figures but to demonstrate how multiple factors influence lender assessments.
How to Improve Your Borrowing Capacity
If you’re planning to buy a property in the future, there are several steps that may help strengthen your borrowing position.
Reduce Credit Card Limits
Many borrowers overlook this.
Reducing unused credit card limits may improve borrowing capacity.
For example:
Current Limit: $30,000
Reduced Limit: $5,000
This may positively impact lender servicing calculations.
Pay Down Existing Debts
Reducing:
- Personal loans
- Car loans
- Credit card balances
can improve financial capacity and reduce lender concerns.
Avoid Taking on New Debt
Major purchases financed through loans before a home loan application may reduce borrowing power.
Increase Your Deposit
A larger deposit can improve loan options and reduce lender risk.
Improve Your Credit Profile
Consistently paying bills and debts on time can strengthen your credit position.
Review Household Spending
Reducing discretionary spending may improve your financial profile and demonstrate stronger savings habits.
Common Borrowing Capacity Mistakes
Assuming Income Is the Only Factor
Income is important, but expenses and liabilities often have an equally significant impact.
Applying with Multiple Lenders
Multiple credit enquiries can negatively affect your credit profile.
Ignoring Credit Card Limits
Even unused limits may affect borrowing assessments.
Borrowing the Maximum Available
A lender’s maximum approval amount may not always align with your personal comfort level.
Failing to Seek Professional Advice
Different lenders have different policies.
The right lender can sometimes make a substantial difference to borrowing outcomes.
Frequently Asked Questions
How Much Can I Borrow Based on My Salary?
There is no simple formula because lenders assess income alongside expenses, debts, and other factors.
Do Credit Cards Affect Borrowing Capacity?
Yes. Even unused credit card limits can impact borrowing assessments.
Can I Increase My Borrowing Capacity?
Potentially. Reducing debt, lowering credit limits, improving savings, and strengthening your financial profile may help.
Does Having Children Affect Borrowing Capacity?
Lenders generally consider dependants because they increase household living expenses.
Why Work with a Mortgage Broker?
A mortgage broker can help:
- Compare multiple lenders
- Assess borrowing capacity
- Identify lender policies that suit your situation
- Structure applications effectively
- Explain available loan options
Rather than relying on a single lender’s assessment, a broker can explore a broader range of possibilities.
The Bottom Line
Borrowing capacity is influenced by much more than income alone.
Lenders assess your overall financial position, including expenses, debts, dependants, employment stability, credit history, and future repayment affordability.
Understanding these factors before applying can improve your chances of approval and help you make better financial decisions.
The earlier you understand your borrowing position, the better prepared you’ll be for your home ownership journey.
Want to Know How Much You Could Borrow?
At Suncrest Finance, we help clients understand their borrowing capacity, compare lender options, and develop strategies to strengthen their home loan applications.
Whether you’re buying your first home, refinancing, upgrading, or investing in property, we’re here to help you navigate the lending process with confidence.
Contact Suncrest Finance today for a complimentary borrowing capacity assessment and personalised lending guidance.