How Refinancing Can Save You Money: A Complete Guide for Australian Homeowners.
Introduction
Many Australians take the time to compare home loans when purchasing a property, but once their loan settles, they rarely review it again.
The reality is that your home loan should not be a “set and forget” financial product.
Interest rates change, lenders introduce new products, property values increase, and your financial circumstances evolve over time.
As a result, a home loan that was suitable five years ago may no longer be the best option today.
This is where refinancing can help.
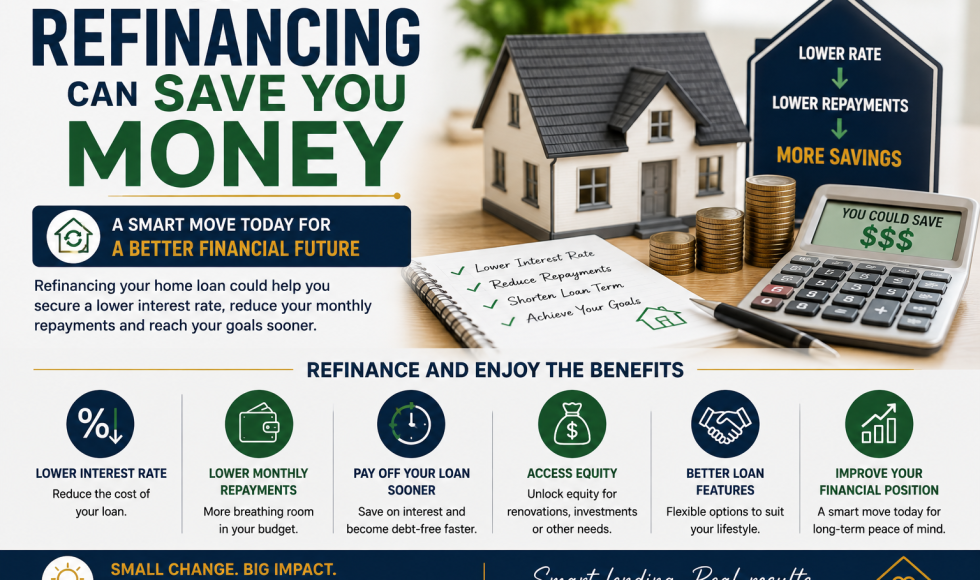
Refinancing may provide opportunities to reduce repayments, save interest, access equity, consolidate debt, and improve your overall financial position.
In this guide, we’ll explain how refinancing works, when it may make sense, and how it could potentially save you money.
What Is Refinancing?
Refinancing involves replacing your existing home loan with a new loan.
This could be:
- With your current lender
- With a different lender
The goal is typically to improve your financial situation.
Borrowers refinance for various reasons, including:
- Lower interest rates
- Better loan features
- Access to equity
- Debt consolidation
- Fixed rate expiry
- Investment strategies
Why Do People Refinance?
Many borrowers are surprised to learn that loyalty doesn’t always result in the most competitive loan terms.
Lenders frequently offer attractive deals to new customers, while existing customers may remain on older products.
This can create opportunities for savings through refinancing.
1. Lower Interest Rates
One of the most common reasons homeowners refinance is to secure a lower interest rate.
Even a small reduction can result in significant savings over the life of a loan.
Example
Current Loan:
- Balance: $700,000
- Interest Rate: 6.50%
Refinanced Loan:
- Interest Rate: 6.00%
A reduction of just 0.50% could potentially save thousands of dollars in interest over time.
The exact savings will depend on loan balance, repayment structure, and loan term.
2. Reduce Monthly Repayments
A lower interest rate may also reduce monthly repayments.
This can improve household cash flow and provide additional flexibility in managing expenses.
Some borrowers use these savings to:
- Build emergency funds
- Invest
- Make additional repayments
- Reduce financial stress
3. Access Better Loan Features
Many older home loans lack modern features that can help borrowers manage their finances more effectively.
Refinancing may provide access to features such as:
Offset Accounts
Reduce the interest charged on your home loan while keeping funds accessible.
Redraw Facilities
Allow access to additional repayments made on the loan.
Flexible Repayment Options
Make extra repayments without penalties.
Digital Banking Tools
Improved online banking and loan management capabilities.
4. Access Equity in Your Property
Property values often increase over time.
As your property’s value rises and your loan balance reduces, you may build equity.
What Is Equity?
Equity is the difference between:
Property Value
minus
Outstanding Loan Balance
Example
Property Value: $1,000,000
Loan Balance: $650,000
Available Equity: $350,000
Some of this equity may potentially be accessed through refinancing, subject to lender policies and approval.
Common Reasons for Accessing Equity
Home Renovations
Improve your property without using savings.
Investment Property Purchases
Use available equity to assist with future investments.
Debt Consolidation
Simplify finances by combining debts.
Education Expenses
Fund major life goals and opportunities.
5. Consolidate Multiple Debts
Many Australians carry several forms of debt, including:
- Credit cards
- Personal loans
- Car loans
These debts often attract higher interest rates than home loans.
Refinancing may allow eligible borrowers to consolidate debts into a single loan structure.
Potential Benefits
Simplified Finances
Manage one repayment instead of several.
Lower Interest Costs
Home loan rates are often lower than unsecured debt rates.
Improved Cash Flow
Reduced monthly obligations may improve budgeting.
Important Consideration
While debt consolidation can provide benefits, extending short-term debt over a longer home loan term may increase total interest paid over time.
Professional advice is important before proceeding.
6. End of Fixed Rate Period
Many borrowers fix their interest rate for:
- 1 year
- 2 years
- 3 years
- 5 years
When the fixed period ends, the loan usually reverts to the lender’s standard variable rate.
In many cases, this rate may not be the most competitive option available.
A fixed rate expiry provides an excellent opportunity to review your home loan.
7. Improve Your Financial Position
Your circumstances may have improved since obtaining your original loan.
For example:
- Higher income
- Reduced debts
- Improved credit history
- Increased property value
These changes may provide access to more competitive lending options.
How Much Could Refinancing Save?
The answer varies significantly between borrowers.
Savings depend on factors such as:
- Current interest rate
- New interest rate
- Loan balance
- Remaining loan term
- Fees and charges
A proper loan review can help determine potential savings.
Costs to Consider Before Refinancing
Refinancing is not always beneficial.
It’s important to consider all associated costs.
Discharge Fees
Some lenders charge fees to close an existing loan.
Application Fees
Certain lenders may charge loan establishment fees.
Valuation Fees
Property valuations may be required.
Government Registration Fees
Mortgage registration and discharge fees may apply.
Fixed Loan Break Costs
Borrowers exiting a fixed-rate loan early may incur break costs.
These costs can sometimes be substantial.
Signs It May Be Time to Refinance
You may wish to review your loan if:
- Your interest rate seems uncompetitive
- Your fixed rate is ending
- You want an offset account
- You need access to equity
- Your financial circumstances have improved
- You haven’t reviewed your loan in several years
Even if refinancing isn’t appropriate today, a review can provide valuable insights.
Common Refinancing Mistakes
Focusing Only on Interest Rates
The lowest rate isn’t always the best loan.
Loan features, fees, flexibility, and service levels also matter.
Ignoring Refinancing Costs
Savings should outweigh any costs involved in changing lenders.
Borrowing More Than Necessary
Accessing equity can be useful, but additional borrowing should align with clear financial objectives.
Not Comparing Multiple Lenders
Different lenders may offer significantly different products and lending policies.
The Refinancing Process
Understanding the process can make refinancing much less intimidating.
Step 1: Review Your Existing Loan
Assess:
- Current rate
- Features
- Fees
- Loan balance
Step 2: Compare Options
Review alternative products across multiple lenders.
Step 3: Calculate Potential Savings
Compare interest savings and refinancing costs.
Step 4: Submit Application
Provide required documentation and complete lender assessments.
Step 5: Valuation and Approval
The lender assesses the property and finalises approval.
Step 6: Settlement
The new lender pays out the existing loan and establishes the new facility.
Frequently Asked Questions
How Often Should I Review My Home Loan?
Many homeowners benefit from reviewing their loan every one to two years.
Can I Refinance with the Same Lender?
Yes.
Some lenders offer retention pricing or loan product changes for existing customers.
Will Refinancing Affect My Credit Score?
A refinancing application may result in a credit enquiry. However, responsible refinancing for genuine financial purposes is common and generally manageable.
How Long Does Refinancing Take?
Timeframes vary depending on the lender, documentation requirements, and settlement processes.
Can I Refinance if My Property Value Has Increased?
Potentially, yes. Increased property values may improve equity and lending options.
The Bottom Line
Refinancing can be one of the most effective ways to improve your home loan and potentially save money.
Whether your goal is to secure a lower interest rate, reduce repayments, access equity, consolidate debt, or obtain better loan features, refinancing may create opportunities to strengthen your financial position.
The key is understanding both the potential benefits and the associated costs before making a decision.
A regular home loan review can help ensure your mortgage continues to support your financial goals.
Is Your Home Loan Still Competitive?
At Suncrest Finance, we help homeowners compare loan options, review existing mortgage structures, calculate potential savings, and determine whether refinancing may be beneficial.
Whether you’re looking to reduce repayments, access equity, or simply understand your options, we’re here to help.
Contact Suncrest Finance today for a complimentary home loan health check and refinancing assessment.
Disclaimer
The information provided in this article is general in nature and does not constitute financial, credit, legal, or tax advice. Lending criteria, fees, charges, and eligibility requirements vary between lenders and may change over time. Consider seeking professional advice tailored to your individual circumstances before making financial decisions.
3 Comments
Riva Collins
December 25, 2018 - 3:33 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghor global and brands, companies are reaching out.
Obila Doe
December 25, 2018 - 3:43 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghorglobal and brands, companies are reaching out.
Arnold Rio
December 25, 2018 - 3:44 pmIt’s no secret that the digital industry is booming. From exciting startups to need ghorglobal and brands, companies are reaching out.