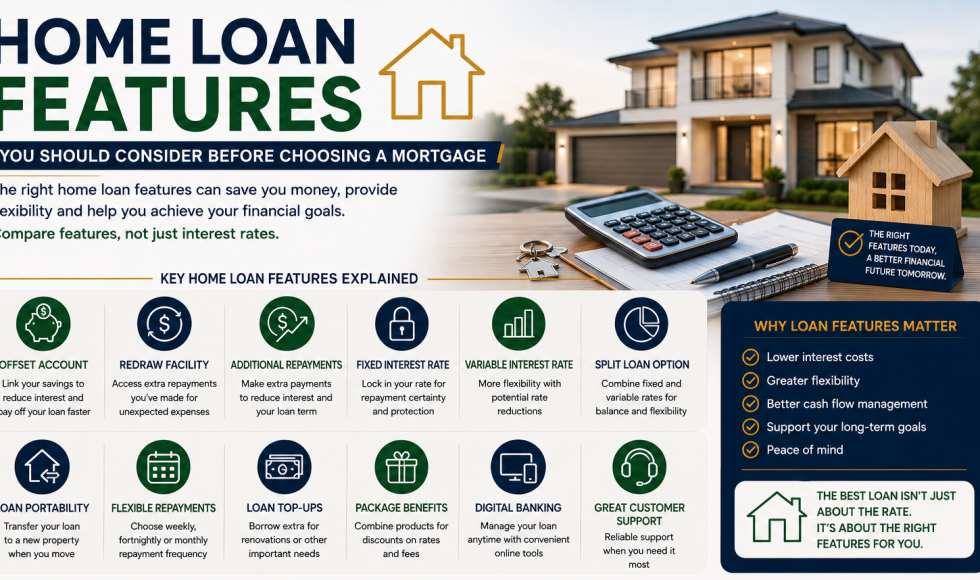
Home Loan Features You Should Consider Before Choosing a Mortgage
Choosing a home loan is one of the most important financial decisions you’ll make, yet many borrowers focus almost entirely on one factor: the interest rate.
While interest rates are undoubtedly important, they don’t tell the whole story.
Modern home loans offer a wide range of features designed to improve flexibility, reduce borrowing costs, simplify money management, and help borrowers achieve their financial goals. A loan with the lowest advertised rate isn’t always the best loan if it lacks the features you need.
Whether you’re a first-home buyer, homeowner, investor, or someone considering refinancing, understanding the available home loan features can help you make a more informed decision.
In this guide, we’ll explore the most important home loan features available in Australia and explain how they can influence your borrowing experience.
Why Home Loan Features Matter
A mortgage is typically a long-term commitment that can last 25 to 30 years.
During that time, your financial circumstances may change significantly.
You may:
- Change jobs.
- Start a family.
- Purchase an investment property.
- Receive a salary increase.
- Experience rising living costs.
- Refinance your loan.
Choosing a loan with flexible features can help you adapt to changing circumstances without having to switch lenders.
When comparing home loans, consider the complete package rather than focusing exclusively on the interest rate.
Offset Accounts
An offset account is one of the most valuable home loan features available.
An offset account is a transaction account linked to your mortgage. The balance in the account reduces the amount of the loan on which interest is calculated.
How an Offset Account Works
Let’s assume:
- Home loan balance: $700,000
- Offset account balance: $50,000
Instead of paying interest on the full $700,000 loan balance, interest is calculated on $650,000.
Benefits of an Offset Account
Lower Interest Costs
Reducing the amount of your loan that attracts interest can save thousands of dollars over time.
Faster Loan Repayment
Less interest means more of your repayments contribute to reducing the principal balance.
Greater Financial Flexibility
Unlike making extra repayments directly into the loan, money in an offset account remains accessible.
Who Should Consider an Offset Account?
Offset accounts are particularly useful for:
- Homeowners
- Property investors
- Borrowers with significant savings
- Families building emergency funds
Redraw Facilities
A redraw facility allows borrowers to access additional repayments they’ve previously made on their mortgage.
If you’ve paid more than your required monthly repayment, you may be able to withdraw those extra funds when needed.
Benefits of a Redraw Facility
Access to Additional Funds
Unexpected expenses may include:
- Home renovations
- Medical costs
- Vehicle repairs
- Education expenses
A redraw facility provides access to funds without requiring a separate loan.
Reduced Interest Costs
Additional repayments reduce the outstanding loan balance, which can lower the amount of interest charged.
Offset Account vs. Redraw Facility
Although both features can reduce interest costs, they’re designed for different purposes.
| Feature | Offset Account | Redraw Facility |
|---|---|---|
| Access to funds | Immediate | May be restricted |
| Money location | Separate account | Additional loan repayments |
| Everyday banking | Yes | No |
| Flexibility | High | Moderate |
Additional Repayment Options
Some home loans allow borrowers to make additional repayments without penalties.
Even small extra repayments can significantly reduce the total interest paid over the life of a loan.
Why Additional Repayments Matter
A borrower who makes regular extra repayments may:
- Pay off the mortgage earlier.
- Reduce interest costs.
- Build equity faster.
Before selecting a loan, determine whether your lender allows unlimited additional repayments.
Fixed Interest Rates
A fixed-rate loan locks your interest rate for a specified period.
Most lenders offer fixed terms ranging from one to five years.
Advantages of Fixed Rates
Repayment Certainty
Monthly repayments remain predictable.
Protection Against Interest Rate Increases
Your repayments won’t increase during the fixed period.
Potential Limitations
Fixed-rate loans may include:
- Break fees
- Restrictions on additional repayments
- Limited offset account functionality
Variable Interest Rates
Variable interest rates fluctuate according to market conditions.
Advantages of Variable Rates
Greater Flexibility
Variable loans often include:
- Offset accounts
- Redraw facilities
- Unlimited additional repayments
Potential Interest Rate Reductions
If market interest rates decline, your repayments may decrease.
Potential Risks
Interest rates can increase, resulting in higher monthly repayments.
Split Loans
A split loan combines both fixed and variable interest rates.
For example:
- 50% fixed
- 50% variable
Benefits of Split Loans
Balanced Risk
Borrowers receive some protection against rising rates while maintaining access to flexible loan features.
Improved Cash Flow Management
A split loan can provide a balance between stability and flexibility.
Loan Portability
Portability allows borrowers to transfer an existing home loan to a new property.
This feature can be useful when moving homes.
Benefits of Loan Portability
Avoid Refinancing
You may be able to keep your current loan instead of applying for a new mortgage.
Potential Cost Savings
Portability may reduce:
- Loan application fees
- Legal costs
- Refinancing expenses
Interest-Only Repayment Options
An interest-only loan allows borrowers to pay only the interest for a specific period.
This feature is commonly used by property investors.
Potential Benefits
- Lower repayments
- Improved cash flow
- Greater investment flexibility
Potential Risks
- Higher long-term interest costs
- Larger repayments after the interest-only period ends
Flexible Repayment Frequency
Many lenders allow borrowers to choose how frequently they make repayments.
Options may include:
- Weekly
- Fortnightly
- Monthly
Why Repayment Frequency Matters
Fortnightly repayments can sometimes reduce the total interest paid because borrowers make the equivalent of one additional monthly repayment each year.
Loan Top-Ups
Some lenders allow borrowers to increase their existing mortgage without refinancing.
This feature is known as a loan top-up.
Common Uses for Loan Top-Ups
- Renovations
- Home improvements
- Debt consolidation
- Large purchases
Important Considerations
Borrowing additional funds increases your total debt and should be considered carefully.
Package Loans
A package loan combines multiple financial products under one arrangement.
A package may include:
- Home loans
- Credit cards
- Transaction accounts
- Offset accounts
Potential Benefits
Interest Rate Discounts
Many package loans offer discounted home loan rates.
Fee Reductions
Some banking fees may be reduced or waived.
Are Package Loans Always Better?
Not necessarily.
Annual package fees may offset some of the potential savings.
Always compare the total cost.
Online and Mobile Banking Features
Technology plays an increasingly important role in managing a mortgage.
When comparing lenders, consider:
- Mobile banking apps
- Online account access
- Real-time transaction monitoring
- Digital document management
Convenient banking tools can simplify day-to-day financial management.
Customer Service and Support
Home loans are long-term financial products.
Strong customer support can be just as important as loan features.
Consider:
- Branch access
- Phone support
- Online chat
- Application assistance
- Response times
A lender with excellent customer service may provide a better borrowing experience.
Questions to Ask Before Choosing a Home Loan
Before selecting a mortgage, ask yourself:
- Will I need an offset account?
- Do I want repayment flexibility?
- Am I planning to refinance in the future?
- Do I need access to extra funds?
- How important is repayment certainty?
Your answers will help determine which features are most important.
How a Mortgage Broker Can Help
Comparing home loans can be challenging.
There are numerous lenders, products, and loan features available in the Australian market.
A mortgage broker can help you:
- Compare multiple lenders.
- Understand loan features.
- Assess borrowing capacity.
- Review loan costs.
- Identify suitable products.
At Suncrest Finance, we believe every borrower deserves clear, transparent, and personalized lending advice.
Our goal is to help clients find loan solutions that align with their financial goals and lifestyle.
Final Thoughts
The lowest interest rate doesn’t always provide the greatest value.
Features such as offset accounts, redraw facilities, flexible repayments, and loan portability can significantly influence your long-term financial outcomes.
Before committing to a mortgage, take the time to compare your options and identify the features that matter most to you.
Choosing the right home loan today can provide greater financial flexibility and peace of mind for years to come.
If you’re looking for professional mortgage guidance, Suncrest Finance is here to help you explore your options and make informed borrowing decisions.
Frequently Asked Questions
Which home loan feature saves the most money?
An offset account is often considered one of the most effective features because it can significantly reduce interest costs.
Is an offset account better than a redraw facility?
Both features have advantages. An offset account provides greater flexibility, while a redraw facility may be suitable for borrowers who regularly make additional repayments.
Are fixed-rate loans better than variable-rate loans?
It depends on your financial goals and risk tolerance. Some borrowers choose a split loan to benefit from both options.
Should I choose a loan with unlimited additional repayments?
If you plan to pay off your mortgage faster, unlimited additional repayments can be a valuable feature.