Tips to Improve Your Credit Score: A Complete Guide for Australian Borrowers
Your credit score is one of the most important factors lenders consider when assessing a home loan application. Whether you’re planning to buy your first home, refinance an existing mortgage, purchase an investment property, or apply for a personal loan, maintaining a healthy credit profile can significantly improve your borrowing options.
Many borrowers only start thinking about their credit score after their loan application has been submitted. Unfortunately, by that stage, negative information on a credit report can delay approval or reduce borrowing capacity.
The good news is that improving your credit score doesn’t usually require major financial changes. Small, consistent financial habits can have a significant impact over time.
In this guide, we’ll explain how credit scores work in Australia, what factors influence your score, and the practical steps you can take to strengthen your credit profile.
What Is a Credit Score?
A credit score is a numerical representation of your creditworthiness. It helps lenders assess the likelihood that you’ll repay borrowed money on time.
In Australia, credit scores are calculated by credit reporting agencies such as Equifax, Experian, and illion.
Although scoring models differ between agencies, most scores generally fall within the following ranges:
| Credit Score | Rating |
|---|---|
| Excellent | 800–1,000 |
| Very Good | 700–799 |
| Good | 625–699 |
| Average | 550–624 |
| Below Average | Below 550 |
Lenders don’t rely solely on your credit score when assessing a home loan application. However, a stronger credit profile can increase your chances of approval and improve your access to competitive loan products.
Why Your Credit Score Matters
Your credit score can influence:
- Home loan approvals
- Interest rates
- Borrowing capacity
- Credit card applications
- Personal loan approvals
- Refinancing opportunities
A healthy credit profile demonstrates responsible financial behavior and may provide lenders with greater confidence when reviewing your application.
How Credit Scores Work in Australia
Australia uses a system called Comprehensive Credit Reporting (CCR).
Unlike older reporting systems that focused primarily on negative information, CCR provides a more complete picture of your financial behavior.
Credit reports may include:
- Repayment history
- Credit applications
- Existing debts
- Credit limits
- Defaults
- Bankruptcy information
Making consistent, on-time payments can positively influence your credit profile.
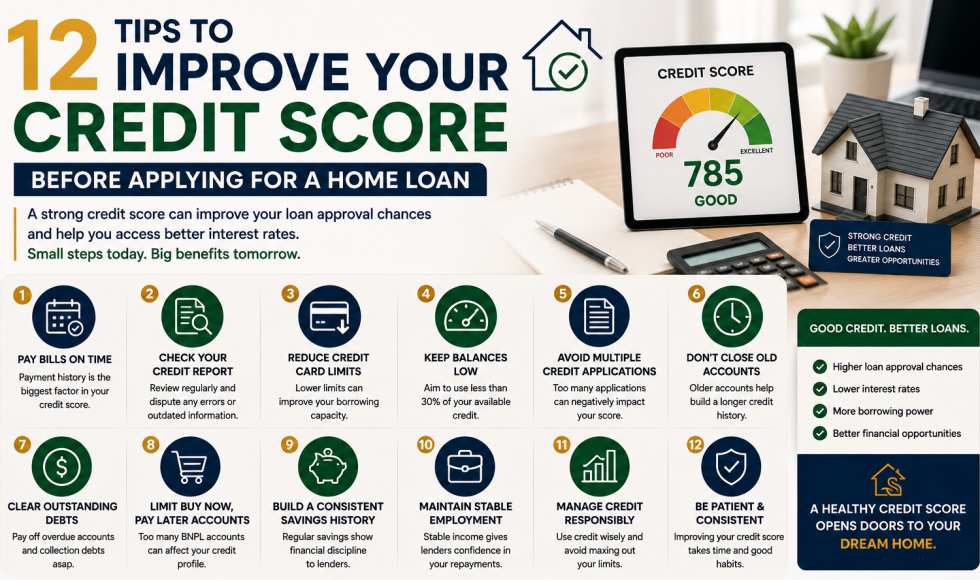
Tip #1: Pay Your Bills on Time
Your repayment history is one of the most important factors affecting your credit score.
Late payments can remain on your credit report and negatively affect future loan applications.
Make it a priority to pay all financial commitments on time, including:
- Credit cards
- Personal loans
- Utility bills
- Phone bills
- Buy-now-pay-later accounts
Setting up automatic payments can help ensure that you never miss a due date.
Tip #2: Review Your Credit Report Regularly
Many Australians don’t check their credit report until they’re preparing to apply for a mortgage.
Reviewing your report regularly can help you identify:
- Incorrect personal information
- Outdated records
- Fraudulent accounts
- Reporting errors
Mistakes can happen.
If you discover inaccurate information, contact the credit reporting agency and request a correction.
Reviewing your report at least once a year is a good financial habit.
Tip #3: Reduce Credit Card Limits
Many borrowers assume that carrying a zero credit card balance means the card won’t affect their borrowing capacity.
However, lenders often assess your approved credit limit, not your current balance.
For example:
| Credit Card | Credit Limit |
|---|---|
| Card 1 | $10,000 |
| Card 2 | $15,000 |
| Card 3 | $5,000 |
Total available credit:
$30,000
Even if you don’t use these cards, lenders may still consider the entire $30,000 limit when evaluating your application.
Reducing unnecessary credit limits may improve both your credit profile and your borrowing capacity.
Tip #4: Avoid Multiple Credit Applications
Every formal credit application can appear on your credit report.
Submitting multiple applications within a short period may signal financial stress to lenders.
Common examples include:
- Credit card applications
- Personal loans
- Car loans
- Store financing
- Buy-now-pay-later services
Instead of applying for multiple financial products, research your options carefully before submitting an application.
Quality is often more important than quantity.
Tip #5: Keep Credit Card Balances Low
High credit utilization can negatively affect your credit profile.
Credit utilization refers to the percentage of available credit you’re currently using.
For example:
Credit card limit:
$10,000
Outstanding balance:
$9,000
Credit utilization:
90%
A lower utilization ratio generally reflects more responsible credit management.
Many financial professionals recommend keeping credit utilization below 30%.
Tip #6: Don’t Close Old Accounts Unnecessarily
The length of your credit history can influence your credit profile.
Older accounts demonstrate a longer history of financial management.
Before closing an account, consider whether maintaining it could benefit your overall credit profile.
However, if an account carries annual fees or encourages unnecessary spending, closing it may still be the right decision.
Every situation is different.
Tip #7: Resolve Outstanding Debts
Unpaid debts can have a significant impact on your credit score.
Addressing outstanding obligations should be a priority.
Common debts that may affect your credit report include:
- Defaulted credit cards
- Overdue utility accounts
- Unpaid personal loans
- Collection agency accounts
If you’re experiencing financial difficulties, contact your lender and discuss available support options.
Ignoring financial obligations rarely improves the situation.
Tip #8: Limit Buy-Now-Pay-Later Services
Buy-now-pay-later services have become increasingly popular.
However, some lenders consider these accounts when assessing home loan applications.
Services such as:
- Afterpay
- Zip
- Klarna
may influence your borrowing profile.
Using these services responsibly and limiting unnecessary accounts can strengthen your financial position.
Tip #9: Build a Consistent Savings History
A strong savings record demonstrates financial discipline.
Lenders often review bank statements to assess your ability to manage money.
A consistent savings pattern can provide evidence that you’re capable of meeting future mortgage repayments.
Simple strategies include:
- Automating savings transfers
- Establishing monthly savings goals
- Creating an emergency fund
Consistency is often more important than the amount you save.
Tip #10: Maintain Stable Employment
Income stability plays an important role in the lending process.
Frequent employment changes don’t automatically reduce your credit score, but they may affect a lender’s assessment of your application.
If you’re planning to apply for a mortgage, maintaining stable employment and avoiding unnecessary financial changes can strengthen your position.
Tip #11: Separate Business and Personal Finances
If you’re self-employed, separating business and personal finances can simplify the lending process.
Maintaining separate accounts helps lenders assess your financial position more accurately.
Clear financial records can improve the efficiency of the loan approval process.
Tip #12: Be Cautious When Acting as a Guarantor
Agreeing to guarantee another person’s loan is a significant financial commitment.
If the borrower fails to meet their obligations, your financial position may be affected.
Before agreeing to become a guarantor, carefully consider the potential risks.
Common Myths About Credit Scores
Myth: Checking Your Credit Report Lowers Your Score
False.
Checking your own credit report doesn’t negatively affect your credit score.
Myth: Paying Off Debt Immediately Repairs Your Score
Not always.
Improving a credit score often takes time.
Positive financial behavior must be demonstrated consistently.
Myth: A Higher Income Guarantees a Better Credit Score
False.
Credit scores are based on financial behavior rather than income.
Even high-income earners can have poor credit profiles.
How Long Does It Take to Improve a Credit Score?
There’s no universal timeline.
The time required depends on factors such as:
- Existing debt
- Payment history
- Credit utilization
- Outstanding defaults
Some improvements may become visible within a few months, while more significant changes may take longer.
Patience and consistency are essential.
How a Mortgage Broker Can Help
A mortgage broker can help you understand how your credit profile may affect your borrowing options.
A broker can:
- Review your financial position
- Assess borrowing capacity
- Identify potential concerns before you apply
- Compare suitable lenders
- Develop a lending strategy aligned with your goals
At Suncrest Finance, we believe that education and preparation are essential components of successful borrowing.
Whether you’re planning to purchase your first home, refinance an existing mortgage, or invest in property, understanding your credit profile can help you make more informed financial decisions.
Final Thoughts
Improving your credit score isn’t about finding a quick fix.
It’s about developing healthy financial habits and maintaining them consistently over time.
Simple actions such as paying bills on time, reducing unnecessary debt, monitoring your credit report, and limiting credit applications can strengthen your financial position and improve your borrowing opportunities.
A strong credit profile can open doors to more competitive loan options and help you achieve your property goals with greater confidence.
If you’re preparing to apply for a home loan and would like professional guidance, Suncrest Finance is here to help.
Frequently Asked Questions
What is considered a good credit score in Australia?
Although scoring models vary, a score above 700 is generally considered good.
Does checking my credit score affect it?
No. Checking your own credit report doesn’t negatively affect your credit score.
Can missed utility payments affect my credit score?
Yes. Overdue utility accounts may appear on your credit report.
How can I improve my credit score quickly?
Pay bills on time, reduce credit card balances, avoid multiple credit applications, and maintain consistent financial habits.